Iran’s saffron competitors were once described by a Khorasan Razavi official as Afghanistan, China and Morocco. His warning was not simply about more hectares abroad. It covered the whole chain—production, processing, trade and marketing—and argued that Iran had to improve all four together.
The archived article, originally titled “Increasing Iran’s saffron competitors,” provides no date for the remarks or supporting production and trade dataset. Its country list should be read as Mohammad Reza Ghodsi’s assessment at the time, not a current ranking.
Who the old report called Iran’s saffron competitors
Ghodsi, identified as Horticulture Director of the Khorasan Razavi Agricultural Jihad Organization, named Afghanistan, China and Morocco as countries becoming serious competitors in saffron production. He linked their interest to the crop’s economic value and lower labour costs.
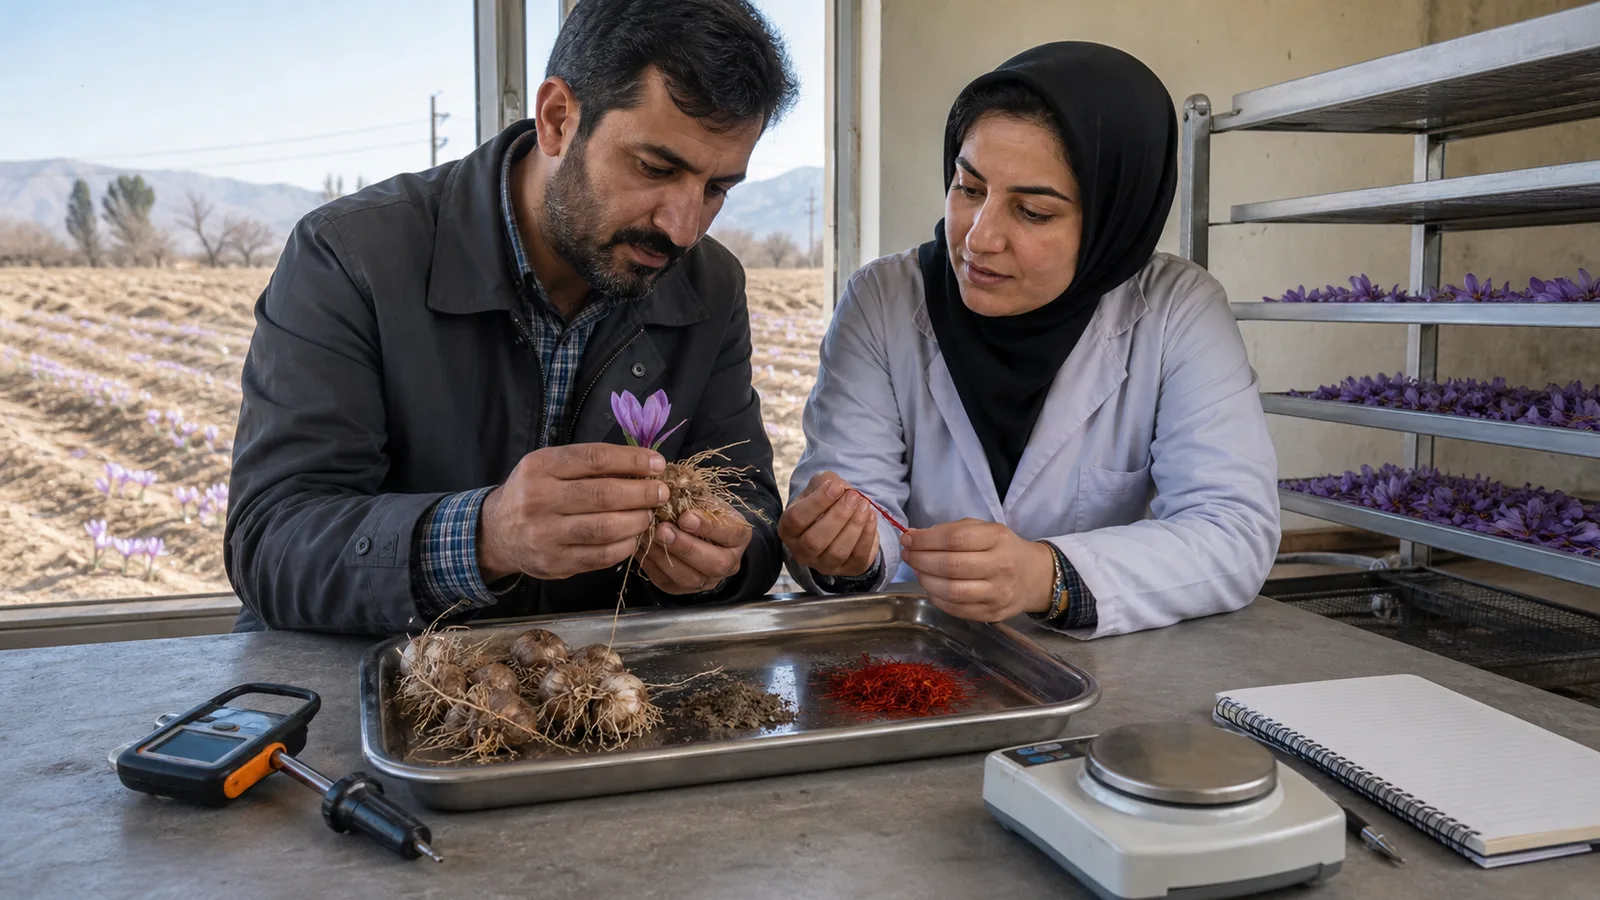
Labour cost is relevant because saffron flowers are picked and their stigmas separated by hand. It is not enough to predict competitiveness. Yield, field life, drying, grading, authenticity, finance, market access, logistics, buyer confidence and the price growers actually receive can outweigh a simple wage comparison.
Current official context still places Iran at the centre of the sector. In 2025, the UN Food and Agriculture Organization said Iran produced about 85–90% of the world’s saffron while facing water stress and growing global competition. That confirms leadership and pressure at the same time; it does not validate every country claim in the older article.
Afghanistan’s saffron sector was more than a prediction
The article said European countries supported saffron planting in Afghanistan as an alternative to poppy. International development programmes did promote legal high-value crops for that purpose, although the history is more complex than the sentence suggests.
A 2020 FAO account of Afghanistan’s saffron value chain described Herat as a major production area and documented support for processing, packaging, hygiene, certification and women-led businesses. The point for Iran is practical: a new producer becomes more competitive when production is connected to the capabilities that buyers require.
Saffron is not a one-for-one substitute for every poppy-growing household. Establishment costs, delayed returns, local security, water, skills and access to committed buyers all affect whether an alternative livelihood lasts.
China and Morocco need evidence, not assumptions
The archived statement also named China and Morocco. It gives no area, output, quality or export figures for either country. Their inclusion is therefore preserved as the official’s warning, not presented as proof that they had already matched Iran’s scale.
“Competitor” can mean several things: a grower selling its own crop, a processor creating higher-value products, a trader serving buyers efficiently, or a country building a reputation for origin and quality. Those roles should be measured separately. Production volume alone cannot show who captures the most value.
Why Spain and the United Arab Emirates appeared in the trade discussion
Ghodsi was translated as saying Spain and the United Arab Emirates had “the most words” in saffron trade. The phrase likely means they had a strong influence or voice in trading, but the article offers no ranking or customs evidence.
A country can be important in saffron trade without growing most of the crop. Importing, sorting, packaging, branding, financing and re-exporting can create market influence. For Iranian producers, that distinction exposes the real risk of selling an agricultural product while other businesses own the customer relationship and the final presentation.
The four connected areas Iran needed to strengthen
Ghodsi said the threats affected production, processing, trade and commerce, and that these sectors had to grow simultaneously. That remains the article’s strongest idea.
- Production: reliable corms, suitable fields, water and soil management, practical extension and records of yield and field age.
- Processing: prompt flower handling, controlled drying, hygienic facilities, lot separation and methods that preserve colour, aroma and bitterness.
- Trade: traceability, testing, compliant documents and packaging, dependable logistics and current destination-market knowledge.
- Commercial development: buyer research, a credible origin story, product formats people want and long-term relationships rather than one-off promotion.
A weakness in any one area can erase gains in another. Higher farm yield does not help if product is damaged after harvest; good saffron cannot command a premium if buyers cannot verify or consistently obtain it.
What the proposed model farms were meant to do
The translation calls “ideal saffron farms” 100% effective and useful, then says there were too few of them. In context, this appears to mean demonstration or model farms: working fields used to teach growers in surrounding villages.
Ghodsi proposed more funding for such farms across Khorasan Razavi and parts of South Khorasan. A demonstration field is useful only when its practices and results are recorded. Growers need to see field age, planting density, water, labour, dried yield, quality and cost—not a showcase plot with no comparable numbers.
The comprehensive saffron programme
The report said a comprehensive programme had identified problems and solutions across production, processing and trade, but required funding to be implemented. It did not publish the programme, budget, timetable or measures of success.
That missing detail matters. A programme should assign responsibility, establish a baseline and measure outcomes such as quality consistency, rejected lots, traceable volume, grower returns, repeat buyers and export value—not only hectares planted or events held.
Exhibitions, embassies and export pricing
Ghodsi suggested international exhibitions, help from embassies and overseas offices, and approval of an export price. Exhibitions and trade offices can introduce suppliers to buyers, but visibility has value only when the product, documentation and follow-up are ready.
The phrase “approving the price” is not explained. A transparent reference price can help market understanding, while a rigid administrative price can become detached from grade, contract terms and demand. The archived article does not provide enough detail to endorse either interpretation.
What staying ahead looks like now
The 2025 FAO and Iran quality-integrity programme focuses on production practice, post-harvest handling, safety, traceability, marketing, authenticity and product innovation. That agenda closely matches the connected risks Ghodsi described.
Iran’s advantage is deep production knowledge and scale. Preserving it means converting those strengths into consistent, verifiable products and direct market trust. The useful response to new saffron competitors is not alarm over a country list; it is better evidence, cleaner processing, stronger traceability and products that buyers choose again.