The supply of Iranian saffron resumed on the Iran Mercantile Exchange after a pause, reopening an early debate about standards, price discovery and futures trading.
“Silver hall” is a journalistic nickname for the commodity exchange, not a physical saffron marketplace. This article preserves a historical stage in the exchange’s development: only 2 kg had traded after several months without a saffron offering, and market participants were still discussing what should come next.
Why the return of a 2 kg supply mattered
Two kilograms was a small transaction beside Iran’s wider saffron trade. Its significance was structural. An exchange sale required the product, seller and transaction to enter a defined trading process, giving buyers and sellers a common venue instead of relying entirely on private negotiation.
The old report described saffron as an important non-oil export with substantial foreign-currency value, but argued that its domestic market still operated largely through traditional channels after roughly 50 years. It also identified bulk exports and weak packaging as persistent barriers to retaining more value inside the producing country.
Those concerns were not unique to the exchange supplier. A 2014 UNIDO diagnostic of Iran’s saffron value chain found that much Iranian saffron was exported in bulk and then processed, packaged, marketed and distributed by firms in destination countries. The report treated stronger processing, packaging and direct market participation as parts of a broader value-chain upgrade.
The case for a clearer trading structure
Hossein Rahiminejad, identified in the archived article as a saffron supplier to the Iran Mercantile Exchange, called saffron a strategic commodity and argued for a clear legal structure for domestic and export sales.
In his view, a transparent framework could reduce the ability of intermediaries to control the market. That was an argument for the exchange model, not proof that every intermediary was unnecessary or that a trading platform alone could solve production, packaging and export problems.
Standardisation was central to the proposal. Exchange-based trade works more clearly when a buyer knows the specified grade, quantity and delivery terms behind an offer. For saffron, a standard can reduce ambiguity, but it does not by itself create good packaging, build an export brand or guarantee a profitable price for growers.
Why Rahiminejad wanted six months before futures
Rahiminejad said the supply of saffron in the exchange’s domestic hall should continue for six months before a futures contract was introduced. His proposed sequence was deliberate:
- build regular spot or physical-market activity;
- allow buyers and sellers to observe transactions and daily price discovery;
- develop familiarity and trust between market participants; and
- launch futures only after participants had enough information to understand the product and its price behaviour.
A futures contract is an agreement to buy or sell a defined amount of a specified commodity at a later date under predetermined terms. It can be used to manage price risk, but it also introduces obligations, margin requirements and the possibility of loss. The original proposal should therefore be read as market-development commentary, not investment advice.
What happened after this early proposal
The article was written before saffron futures became an established part of the exchange. A later 2019 COMCEC Capital Markets Regulators Forum report records Iran’s introduction of saffron warehouse receipts and futures contracts as a commodity-market development.
That later milestone confirms that the proposed futures market was eventually implemented. It does not turn the old 2 kg transaction into a current volume figure, nor does it prove that exchange trading resolved every concern raised about farm income, intermediaries, packaging or exports.
What an exchange can and cannot change
A commodity exchange can create common contract terms, a visible transaction record and a route for standardised goods. Warehouse-based systems can also connect a tradable document to a measured quantity of product held under defined conditions.
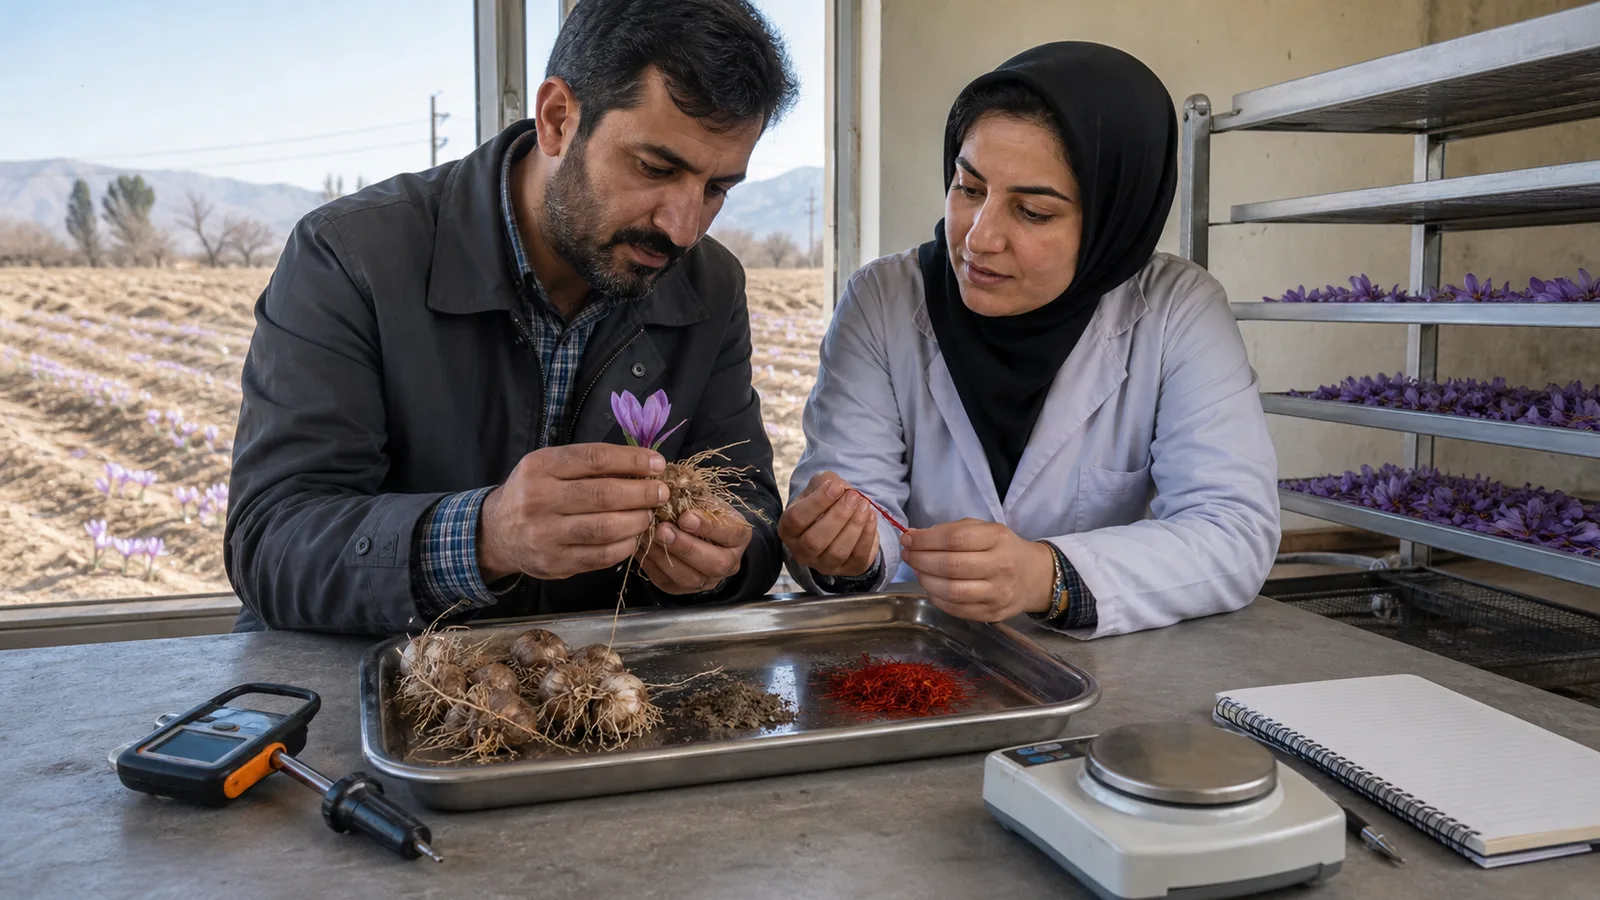
Its limits are just as important. Saffron quality begins before trading, with corm health, field management, timely flower collection, clean stigma separation and controlled drying. Export value also depends on packaging, traceability, market access and buyer relationships. None of those jobs disappears when a contract is listed.
Rahiminejad’s final request reflected that reality. He asked the Iran Mercantile Exchange to provide the practical foundations for a future market, including conditions that would help buyers and sellers become familiar with one another and develop confidence in the process.
Reading the “silver hall” report today
This is best understood as an early-market snapshot. Saffron supply had returned after a gap; 2 kg had traded; a supplier wanted six months of continued activity; and futures were still being discussed as a later step.
The larger ambition was to move Iranian red gold toward more standardised, transparent domestic and export trading. Later warehouse-receipt and futures activity shows that the market infrastructure advanced, while the original concerns about product quality, packaging and the share of value retained by producers remained wider than any single exchange could address.